
Every time someone opens a mobile money account, applies for a digital loan or sends money to family abroad, their personal data travels with them. Two sets of authorities have a stake in that journey: those that protect personal data and those that oversee financial services. When they work together, people can trust digital finance and new providers can enter with confidence. When they don't, questions go unanswered, and customers and firms bear the cost.
A new report by Financial Innovation for Impact (Fii), in collaboration with the Cambridge Centre for Alternative Finance (CCAF), looks at how well that bridge is working in ten emerging markets and developing economies, and how to strengthen it. 'Joined-Up Regulation: Coordination Between Data Protection and Financial Authorities in Emerging Markets' is supported by the Gates Foundation. It covers Brazil, Ethiopia, India, Indonesia, Kenya, Nigeria, Pakistan, the Philippines, South Africa and Uganda.
Why the bridge matters
As finance has become a data business, financial regulation and data protection have come to govern many of the same activities, firms and records. No single authority can regulate digital financial services alone. Trust in how data is used, lawful sharing of fraud signals, open finance and fair AI-driven credit all depend on the two working together. The same lessons apply to the other regulatory boundaries that digital finance increasingly crosses, from competition to telecommunications.
What we found
The foundations are already in place. Where a data protection authority is operating, the legal tools to coordinate generally exist. Half the focus countries have statutes that direct coordination or provide for delegation or sectoral codes. Regulators on both sides told us they want to work together more.
The missing piece is institutional. Coordination that does happen is often improvised: bilateral, event-driven or dependent on individuals.
Timing matters. Data protection authorities are often brought in after financial-sector frameworks are designed, when fixing problems is costlier.
Unsettled questions have a cost. It falls hardest on smaller providers, and on low-income consumers, women and rural users who have the fewest alternatives.
There is a window. Where a data protection authority is still being established, coordination can be built in from the start, which is far easier than retrofitting it later.

“Data protection and financial regulators want many of the same things: innovation, competition, consumer protection, trust. What they often lack is a system for pursuing those goals together. The encouraging news from this research is that the building blocks already exist, as does the desire for change. What's needed are leaders and public servants ready to take the right next steps.”
- Max Bentovim, Data Protection Lead, Fii
What effective cooperation looks like
The report sets out seven practical recommendations, each with a first step authorities can take now, mostly under powers they already hold. They start small:
pick one shared problem, such as fraud-data sharing, and show a result within a year;
name counterparts and referral routes so consumers know who answers;
bring the data protection authority in when new frameworks are designed;
develop guidance jointly.
From there, they build towards cross-training, measuring and reporting on coordination, and joining up national work with regional and international standard-setting.
To help authorities see where they stand, the report also proposes a Regulatory Coordination Index (RCI). The RCI scores how far coordination is in place across the regulatory cycle, from information sharing to joint supervision. It is illustrated for the ten focus countries and designed for authorities to use as a self-assessment tool.
“As finance becomes a data business, many of the hardest questions in financial regulation now sit at its boundary with data protection: fraud, open finance, AI in credit. Building a bridge across that boundary is becoming a core regulatory capability. This research shows that much of what authorities need is already in place; the task now is to build the institutional habits that put it to use.”
- Pavle Avramovic, Director of Research and Policy, Fii
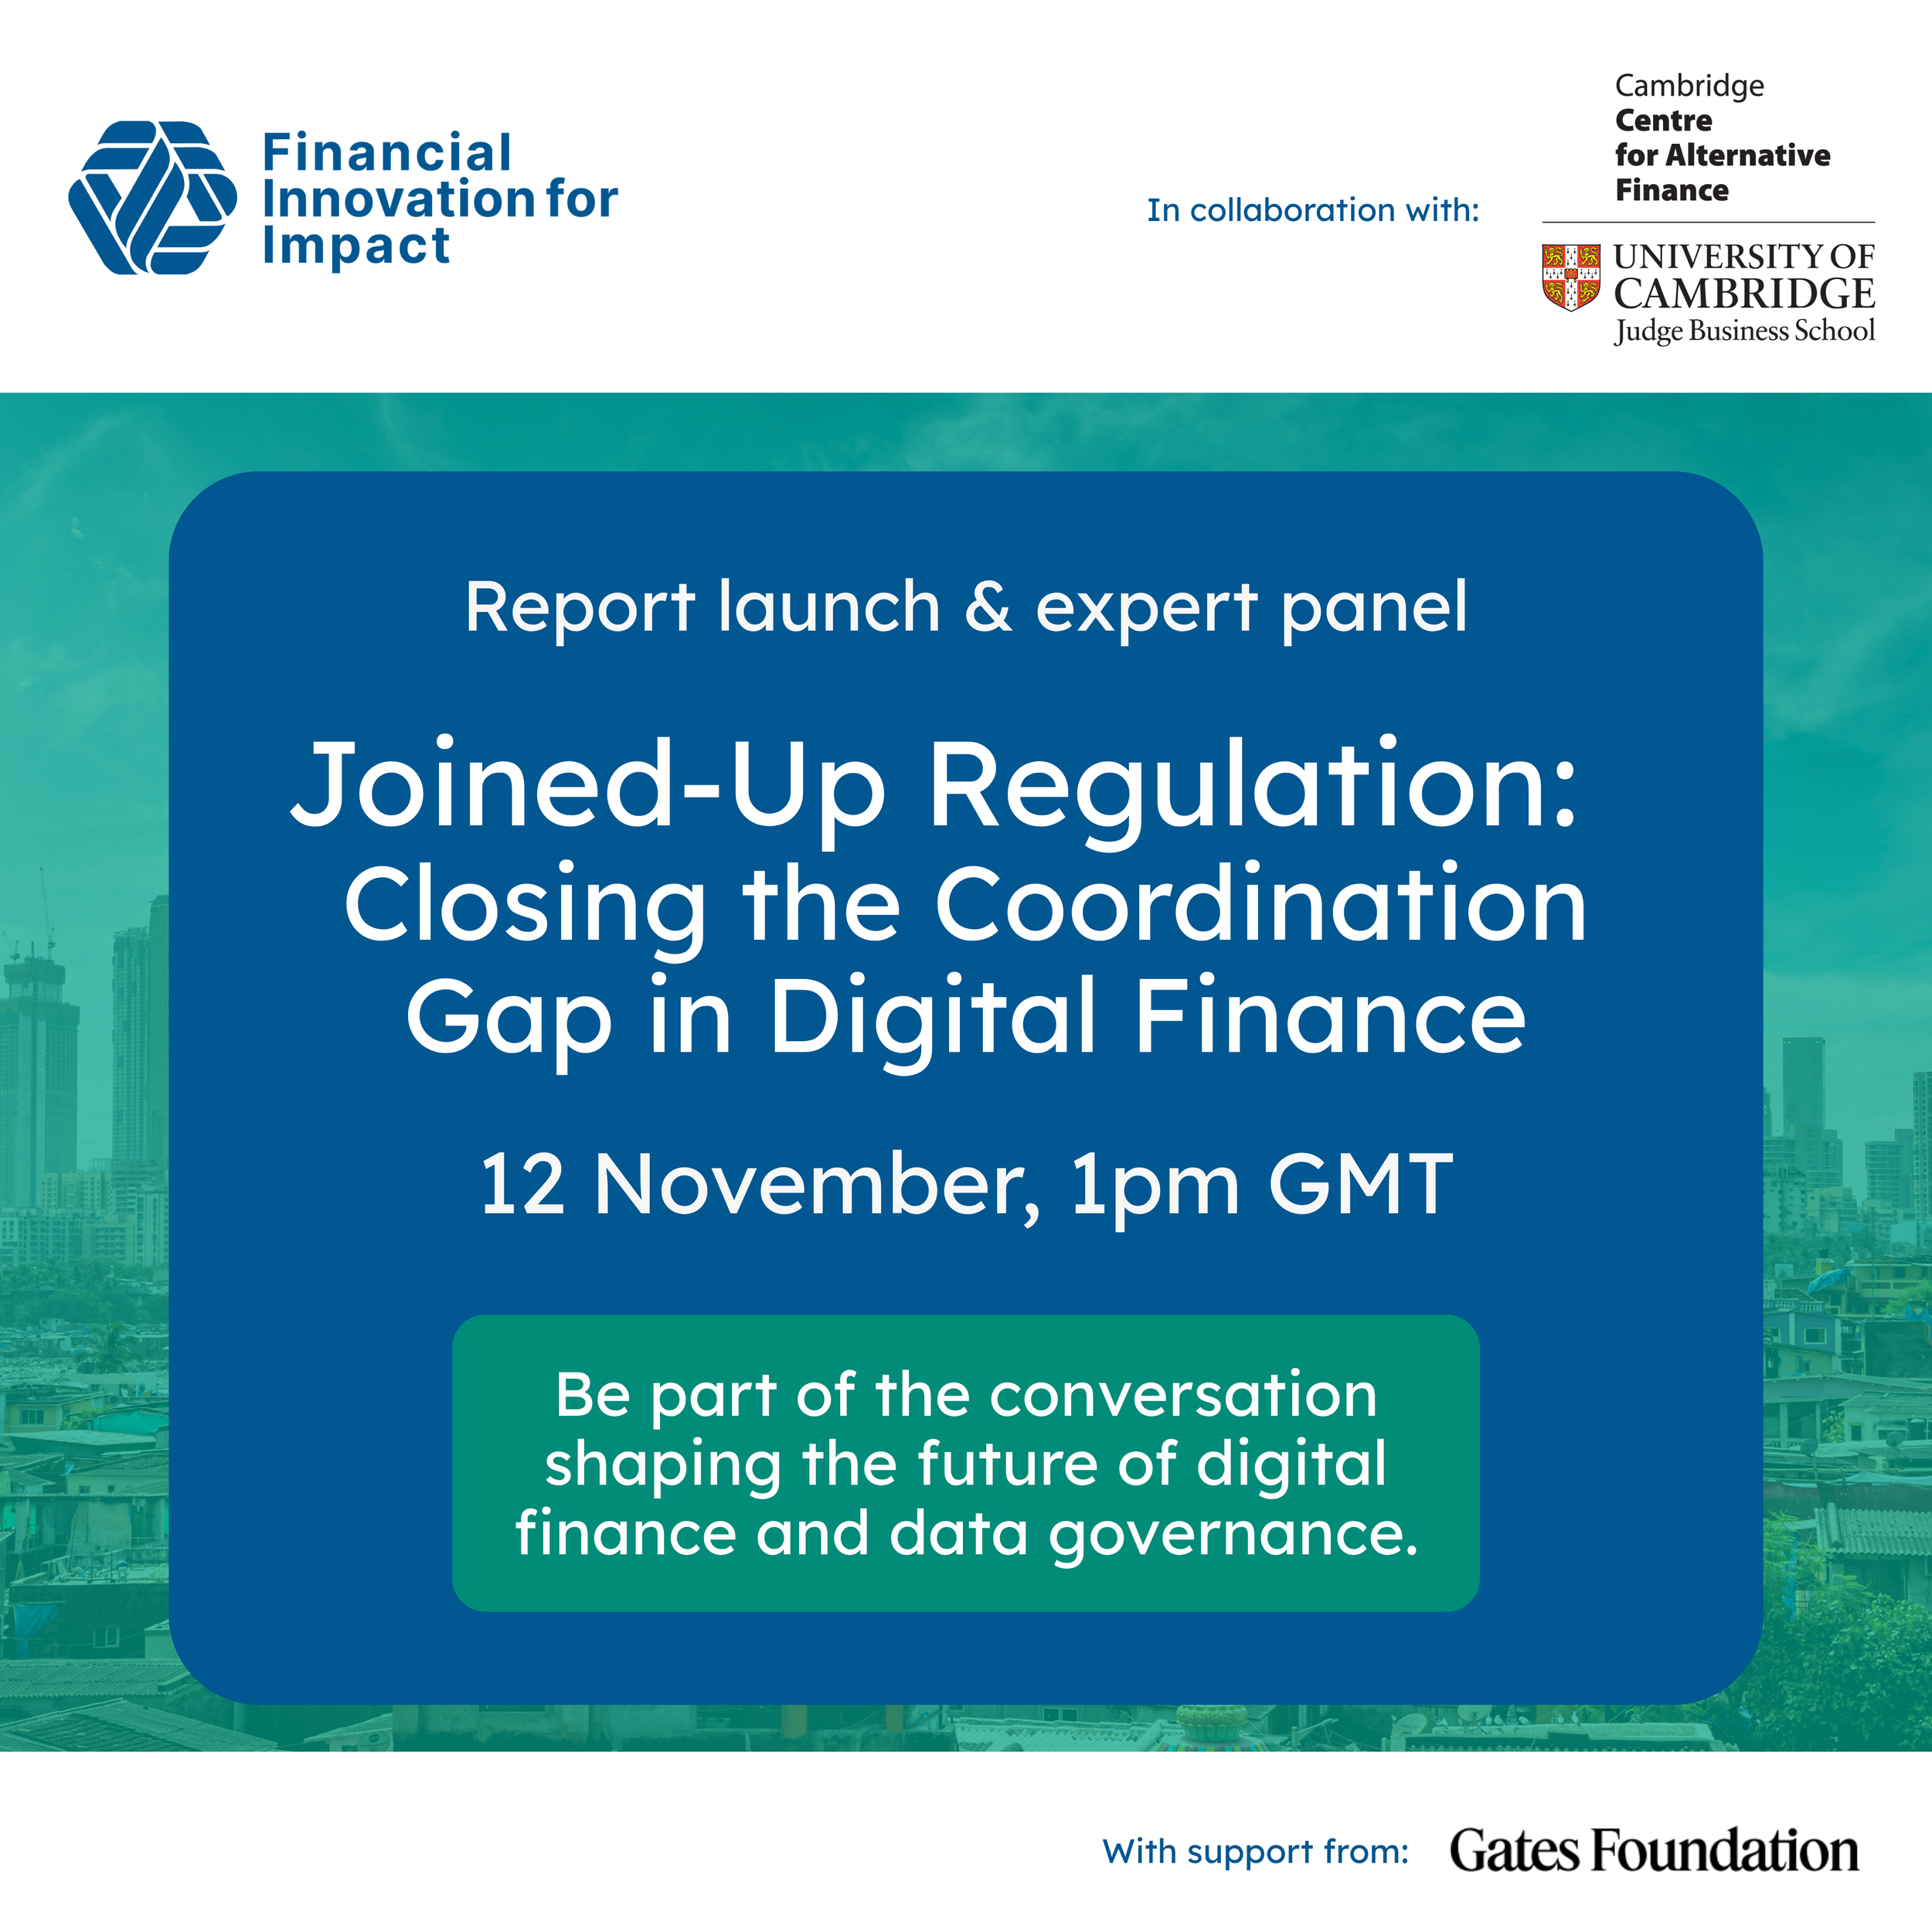
Join the conversation
Sign up for our 12 November webinar, Joined-Up Regulation: Closing the Coordination Gap in Digital Finance, to gain insights from a panel of regulators and experts discussing what effective coordination looks like in practice, why it matters now, and where progress can begin.
Whether you're a regulator, policymaker, fintech leader or development practitioner, this webinar will offer valuable insights into one of the most important governance challenges facing digital financial services today.
Register now and be part of the conversation shaping the future of digital finance and data governance!
Further resources and information
Early findings were discussed in our September webinar, with speakers from the Financial Stability Board, the National Privacy Commission of the Philippines, the State Bank of Pakistan and the Alliance of Digital Finance and FinTech Associations.
The report is accompanied by ten country case studies and a mapping of regional and global initiatives.
To get involved, contact Max Bentovim at max.bentovim@fii.international.